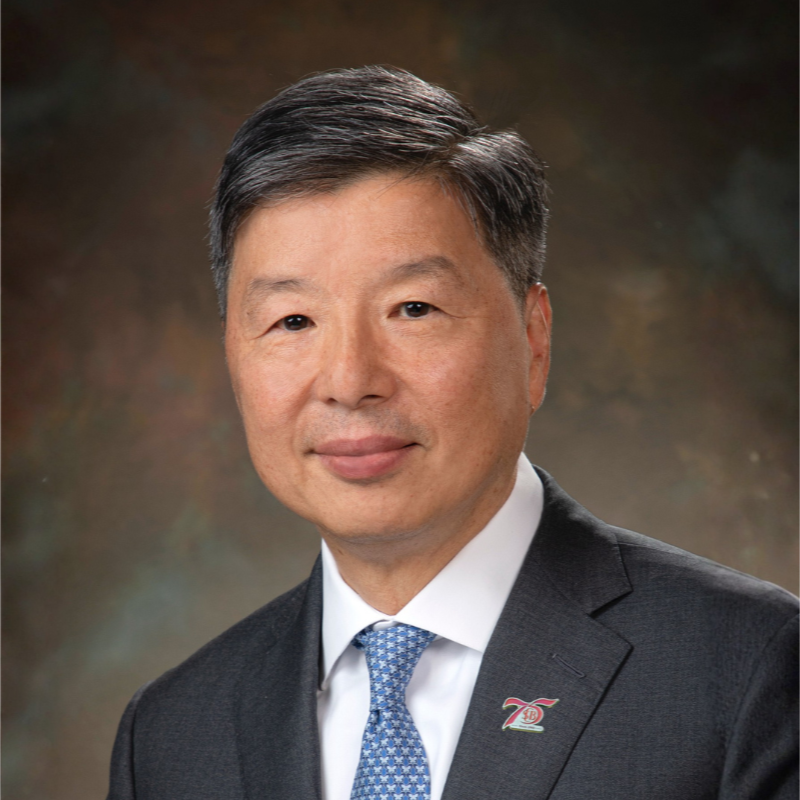
SUNNY'S SIGNAL
As AI takes on more responsibility in banking, we must preserve the human relationships, accountability and empathy on which trust depends.
Key points
- AI’s assistive role is helping banks improve efficiency, fraud detection, credit analysis and customer understanding.
- Agentic AI brings a new leadership question: what authority should banks delegate, and where must people remain involved?
- Clear oversight and accountability must develop alongside autonomy, preserving relationships, trust and empathy.
From better information to delegated authority
AI’s role in banking today is largely assistive. It helps banks improve efficiency, strengthen fraud detection, sharpen credit analysis and make better use of customer analytics. These applications give our people better information and support more informed decisions.
The next phase is agentic AI: agents that can act, decide and execute tasks within defined authority on behalf of a bank or its customers. This changes the leadership challenge. We need to consider how much authority to delegate, under what conditions and who remains responsible for the outcome.
Start with the customer outcome
The value of AI should be judged by what it improves for the customer. A faster process matters, but so do the quality of the decision, the clarity of the explanation and the ease of getting help when something goes wrong.
As banks consider more autonomous services, the question is whether they make banking more useful and dependable. Efficiency gains should create room for better service and more meaningful customer conversations.
Be clear about the division of responsibility
The division of responsibility between people and AI needs to be explicit. Routine activities with clear boundaries may lend themselves to delegation. Decisions with lasting consequences for customers require closer scrutiny and appropriate human judgement.
Before an agent is authorised to act, a bank should be able to answer some practical questions: What may it do? Within whose authority? When must it stop and refer to a person? Who takes responsibility if the outcome is wrong? When acting on a customer’s behalf, it must also be clear what the customer has authorised.
Oversight must work in practice. The people responsible need enough information and authority to question a decision, intervene and put things right. Accountability has to remain clear even as more of the work is performed by AI.
Preserve human connection at the moments that matter
The central challenge is preserving relationships, trust and empathy as banking becomes more automated. Customers may welcome speed and convenience for everyday transactions, yet still need someone to listen when they face financial difficulty, suspected fraud or an unfamiliar decision.
We must make sure that a more automated service does not make it harder to reach a person who can help. Used thoughtfully, AI can give banking colleagues more time for those conversations. Human connection should become more valuable as routine work becomes easier to automate.
Develop people alongside the technology
This transition calls for shared leadership across business, operations, risk and technology. Colleagues need to understand when to rely on AI, when to challenge it and when a customer’s circumstances call for a different response.
The next phase of banking will ask us to bring greater autonomy and human responsibility together. The measure of progress should be better service, clear accountability and relationships that customers continue to trust.
AVER SOLUTIONS PERSPECTIVE
Sunny’s emphasis on human accountability raises a wider question for banks: how can customers trust both what they are told and what is done on their behalf? At AVER Solutions, we believe that trust depends on consistency between how a bank is represented through AI, the promises it makes and the service it delivers. Clear explanations of capabilities, limitations and access to human support should accompany greater autonomy.
That consistency should be tested in practice. Banks can examine whether AI answers accurately describe their services, whether customers understand what they have authorised and whether someone can intervene when help is needed. These checks connect AI visibility with service delivery and give leaders practical evidence of where improvements are needed. Progress should be judged through better customer understanding, dependable service and clear accountability, alongside efficiency.
ABOUT AVER SIGNALS
AVER Signals, published by AVER Solutions, brings together perspectives from leaders across insurance, banking, technology and transformation, alongside clearly attributed company reflections. Each contribution explores a practical question: as AI reshapes our industry, what should leaders prepare for, and how can we use AI to work smarter, serve customers better and strengthen trust?
The aim is not to predict the future, but to help our industry prepare for it through clear, practical and responsible leadership perspectives.
Questions leaders should consider
How is agentic AI different from assistive AI in banking?
What should banks clarify before allowing AI agents to act?
Where should banks preserve human involvement and empathy?
How can banks connect AI visibility with customer trust and business value?